• About
  • Advertise
  • Privacy & Policy
  • Contact
All Access London
Advertisement
  • Home
  • General
  • Celebrity
  • News
    • London
    • UK
    • Business
    • Politics
    • Science
  • Tech
    • Apps
    • Gadgets
    • Mobile
    • Startup
  • Entertainment
    • London Ent.
    • Gaming
    • Movies
    • Music
    • Sports
    • TV
  • Lifestyle
    • Fashion
    • Food
    • Health
    • Travel
  • Reviews
No Result
View All Result
  • Home
  • General
  • Celebrity
  • News
    • London
    • UK
    • Business
    • Politics
    • Science
  • Tech
    • Apps
    • Gadgets
    • Mobile
    • Startup
  • Entertainment
    • London Ent.
    • Gaming
    • Movies
    • Music
    • Sports
    • TV
  • Lifestyle
    • Fashion
    • Food
    • Health
    • Travel
  • Reviews
No Result
View All Result
All Access London
No Result
View All Result
Home News UK

What is the 4% pension rule and does it still work with the rising cost of living?

All Access London Team by All Access London Team
August 13, 2026
in UK
0
What is the 4% pension rule and does it still work with the rising cost of living?
0
SHARES
1
VIEWS
Share on FacebookShare on Twitter


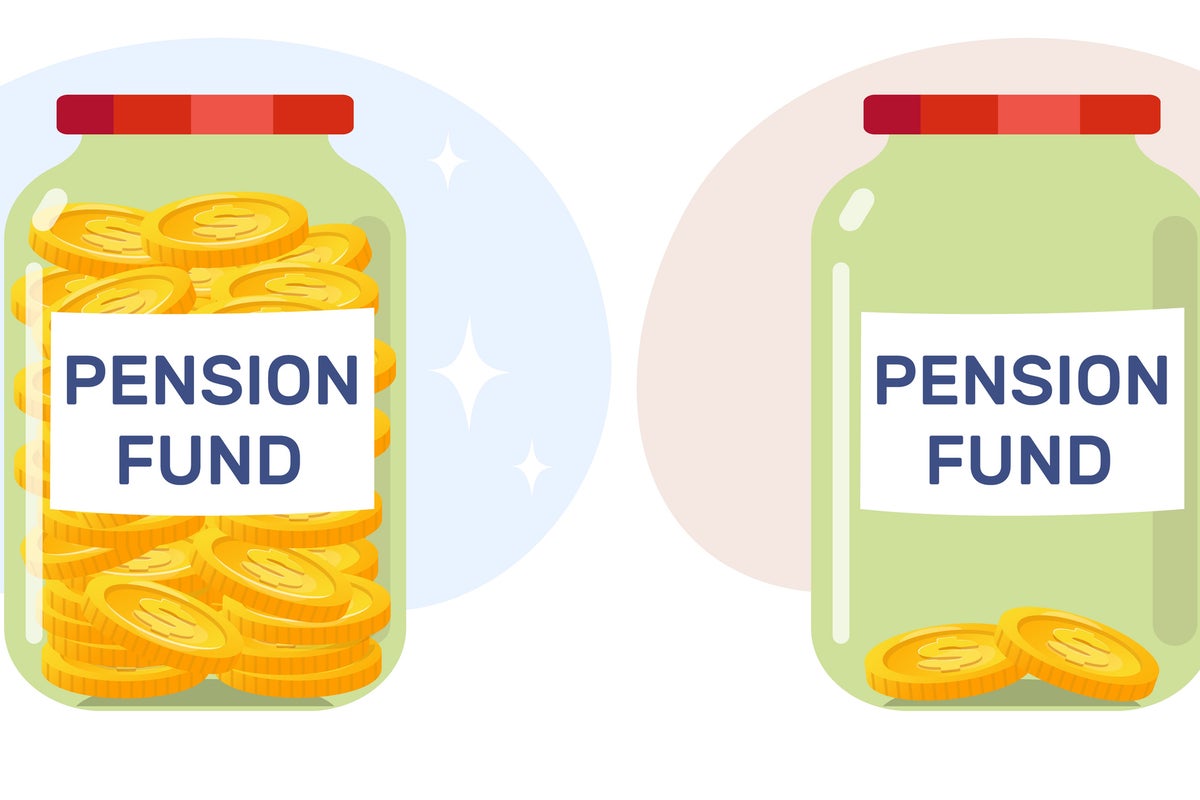
How much you can safely withdraw from your pension is one of the biggest questions in personal finance.

Withdraw too much, and your savings could run out, leaving you with state pension income only. Withdraw too little, and you could leave most of your savings behind, having lived unnecessarily frugally.

There’s a widely known rule that you can safely withdraw four per cent of your pension pot each year.

But is this figure still accurate in 2026, and will it provide the income you need?

How does the four per cent pension rule work?

The rule dictates that if you withdraw from your pension at a rate of four per cent per year, you can expect your pension savings to last for at least thirty years – enough to cover retirement for most people.

So, if you retired today with pension wealth totalling £100,000, you could withdraw £4,000 in the first year.

You’re then allowed to increase your annual withdrawal amount in line with inflation.

If inflation rose at two per cent per year (which is the Bank of England’s target rate), you would withdraw £4,080 in year two, £4,162 in year three, and so on. This wouldn’t give you more to spend (as prices would be rising at the same rate) but would allow your income to keep pace with the rising cost of living.

Rising prices, or inflation, means the same amount of cash has less buying power over time (Getty Images)

Who created the four per cent pension rule?

In 1994, a financial planner and author named William Bengen set out to establish the safest rate of pension withdrawal, looking at actual possible outcomes in previous years.

He used an example portfolio of 50 per cent equities and 50 per cent bonds and calculated how long it would have lasted in real market conditions, if it were first accessed in any year dating back to 1926.

Trading 212 logo

Get a free fractional share worth up to £100.
Capital at risk.

Terms and conditions apply.

Go to website

ADVERTISEMENT

Trading 212 logo

Get a free fractional share worth up to £100.
Capital at risk.

Terms and conditions apply.

Go to website

ADVERTISEMENT

This period includes major market events such as the 1929 crash which preceded the Great Depression and the 1973-75 recession.

With a four per cent withdrawal rate, he found that it would have taken no fewer than 33 years for the fund value to reach zero.

By comparison, a five per cent withdrawal rate would have depleted the fund in as little as 20 years in several cases, which many people would find is not long enough to support their full retirement.

How much income does that give me a year?

According to 2022 data from the Office for National Statistics, the median figure for pension wealth at the ages of 65 to 74 is £191,600 for men and £106,300 for women.

If we use those figures to represent a husband and wife, both of whom also receive the full state pension (presently £12,547.60 a year), we can calculate that their combined annual income (assuming no other sources or savings) would be approximately £37,000, in today’s money. That’s made up of:

  • A combined pension pot of £297,900
  • At 4 per cent, that means £11,916 in the first year
  • Plus the two lots of full state pension.

So, one potential drawback for the rule is that it’s not particularly generous. Another is that it’s inflexible, allowing for no one-off withdrawals for experiences or special purchases.

Many people will wonder if they can afford to relax the rule a little, at least in some years.

Can I safely withdraw more from my pension?

It’s worth noting that the four per cent rule is based on the single worst-case scenario in Bengen’s study. It allows your pension to withstand an event on the scale of the Great Depression, not just normal market conditions.

Most scenarios he calculated had significantly better outcomes.
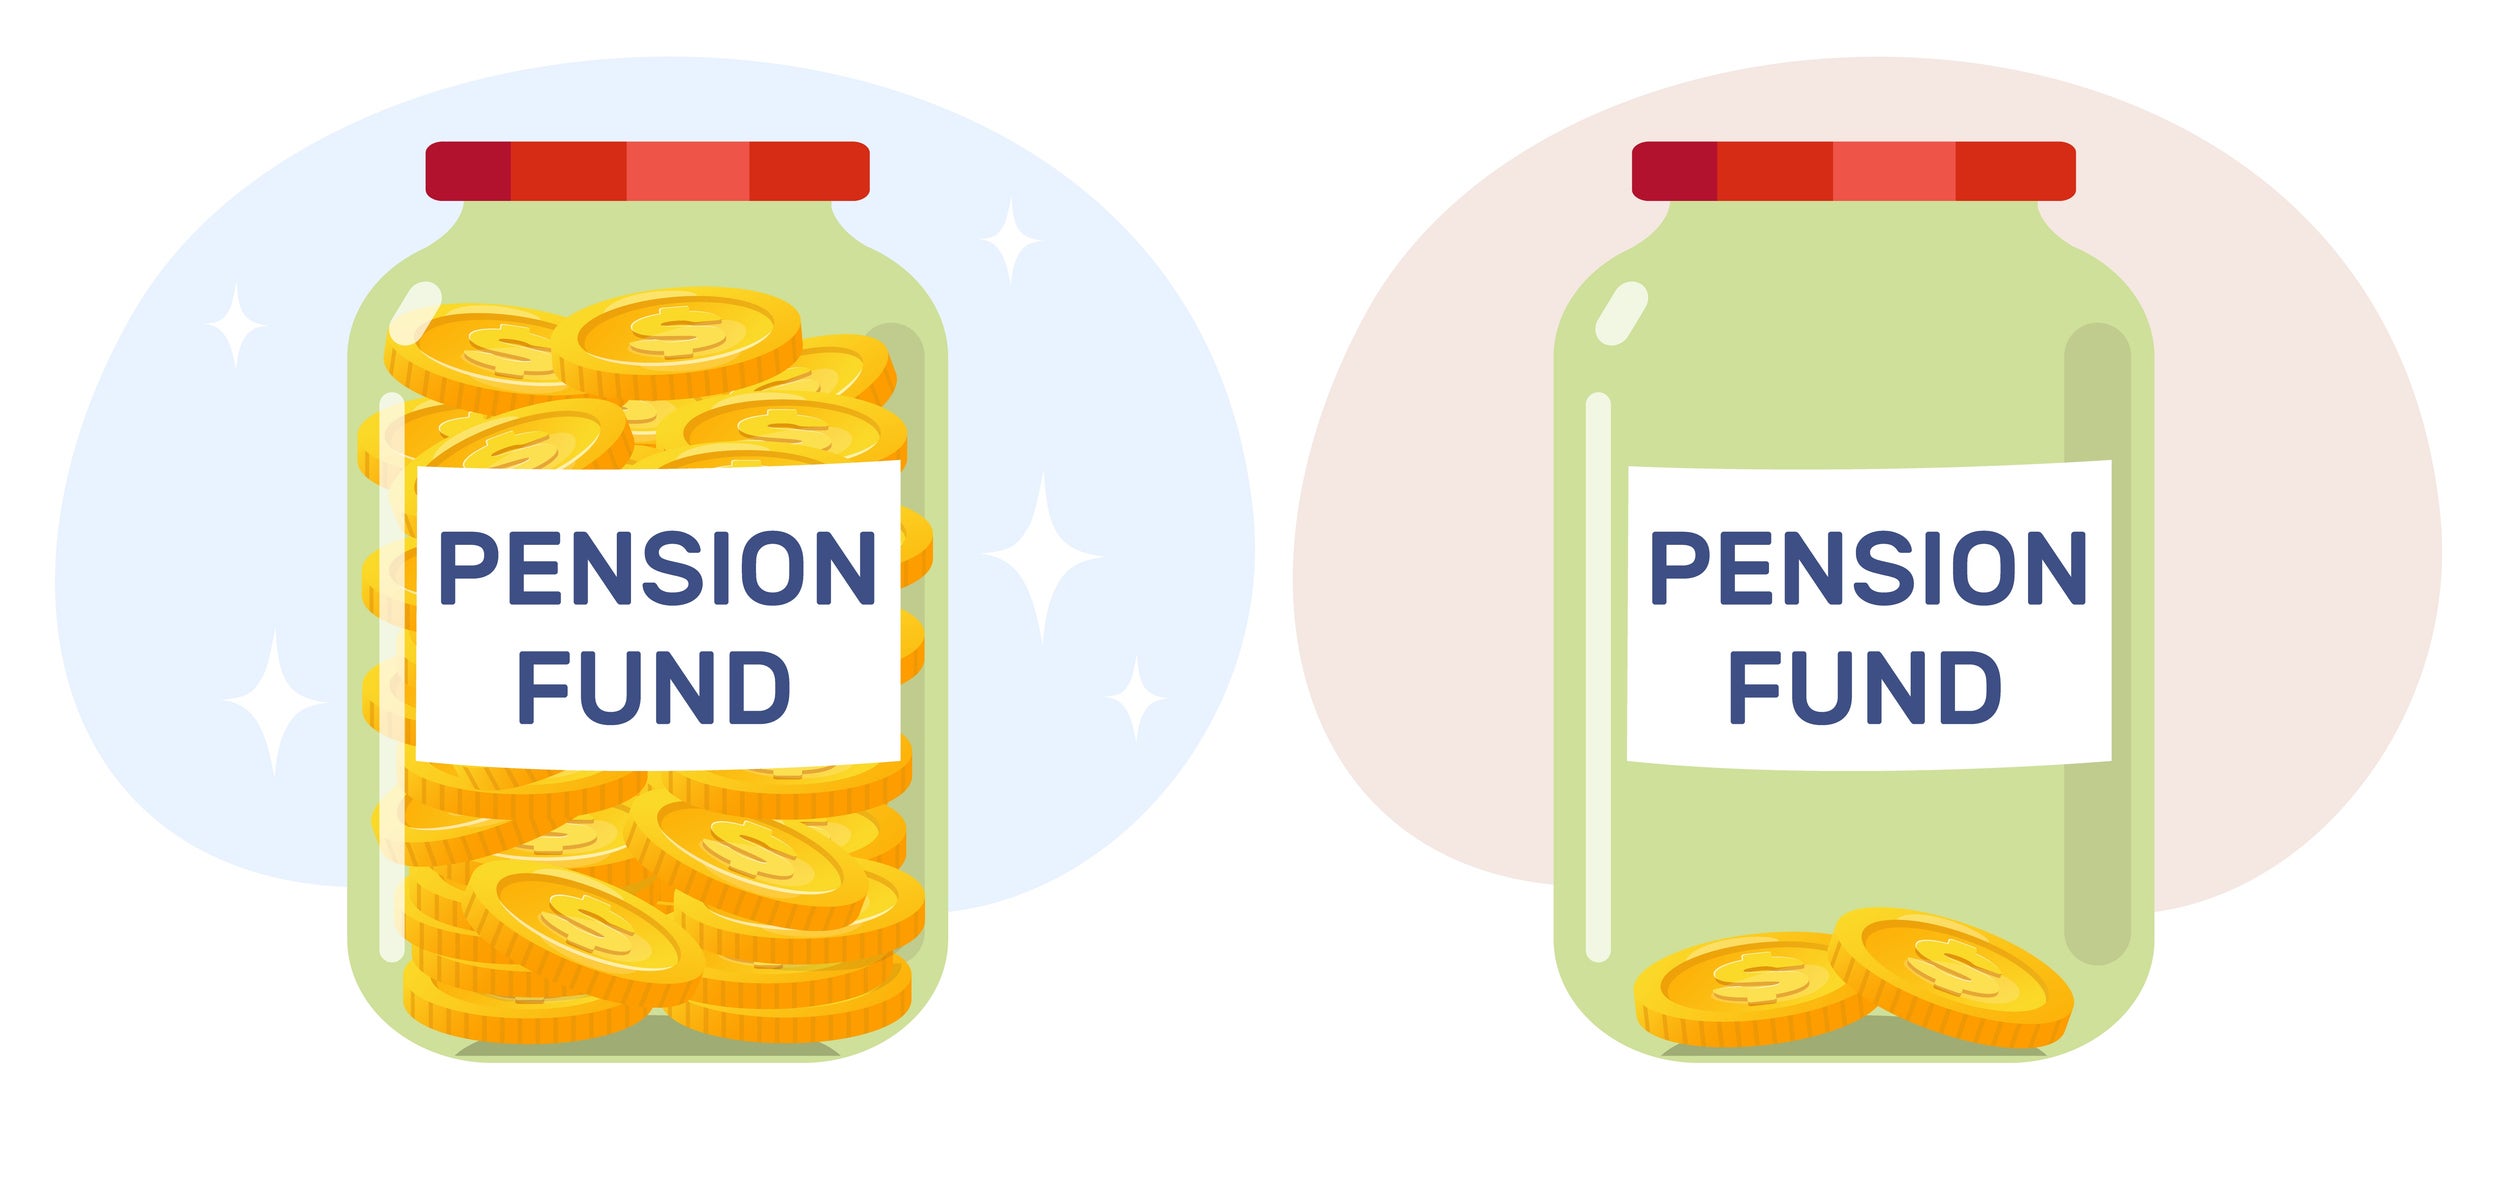
Market conditions impact how much you can safely withdraw from your pension
Market conditions impact how much you can safely withdraw from your pension (Getty/iStock)

In 40 out of 50, a four per cent withdrawal rate would have lasted at least 50 years – far longer than most people would need. This rose to 47 out of 50 when he changed the example portfolio construction to 75 per cent equities and 25 per cent bonds.

Bengen himself has recently stated that, based on current market trends, he considers 4.7 per cent to be the modern equivalent of the four per cent rule (for those wanting to prepare for the worst possible outcomes) and that 5.5 per cent would be more realistic in most cases.

What are my other pension options?

Though the four per cent rule is starting to look overly cautious, it’s still not your best option if you want complete security, as it doesn’t guarantee an income for life.

Instead, you might consider a lifetime annuity that increases in line with inflation.

If you’re comfortable leaving your pension invested and making annual withdrawals, you might decide you need professional help setting an appropriate withdrawal rate and reviewing it regularly. Financial advice could be cheaper than the cost of getting it wrong.

When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results.


Source link

Tags: costlivingpensionrisingruleWork
Previous Post

Residents urge West London council ‘listen to us’ with popular tip set to close

Next Post

A-level results day: Everything you need to know and timings for this year’s results

All Access London Team

All Access London Team

Next Post
A-level results day: Everything you need to know and timings for this year’s results

A-level results day: Everything you need to know and timings for this year’s results

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

  • Trending
  • Comments
  • Latest
Coronation Street cast 2026 | Joining, leaving, returning characters

Coronation Street cast 2026 | Joining, leaving, returning characters

May 9, 2026
Who are Andy Burnham’s key aides and allies? | Andy Burnham

Who are Andy Burnham’s key aides and allies? | Andy Burnham

May 23, 2026
Trade London for Brighton This Weekend

Trade London for Brighton This Weekend

May 7, 2026
Independence Day 2026 Events: Where To Celebrate 4 July In London

Independence Day 2026 Events: Where To Celebrate 4 July In London

May 8, 2026
Merton roads being resurfacing or repaired this year from Mitcham to Wimbledon – full list

Merton roads being resurfacing or repaired this year from Mitcham to Wimbledon – full list

1
The World Naked Bike Ride Returns To London This Summer

The World Naked Bike Ride Returns To London This Summer

0
London's Hidden Roman Bathhouse Reopens For Tours

London's Hidden Roman Bathhouse Reopens For Tours

0
Bring Out The Bunting: St George's Day Celebrations Are Coming To Trafalgar Square

Bring Out The Bunting: St George's Day Celebrations Are Coming To Trafalgar Square

0
David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

November 10, 2026
Five key accounts from women in Guardian and ITV’s David Walliams investigation

Five key accounts from women in Guardian and ITV’s David Walliams investigation

November 10, 2026
Moment brazen thief snatches phone in plain sight at London pub

Moment brazen thief snatches phone in plain sight at London pub

November 10, 2026
‘A robbery in London’s Ted Lasso filming spot inspired me to take on Sadiq Khan as Mayor’

‘A robbery in London’s Ted Lasso filming spot inspired me to take on Sadiq Khan as Mayor’

November 10, 2026

Recent News

David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

November 10, 2026
Five key accounts from women in Guardian and ITV’s David Walliams investigation

Five key accounts from women in Guardian and ITV’s David Walliams investigation

November 10, 2026
Moment brazen thief snatches phone in plain sight at London pub

Moment brazen thief snatches phone in plain sight at London pub

November 10, 2026
‘A robbery in London’s Ted Lasso filming spot inspired me to take on Sadiq Khan as Mayor’

‘A robbery in London’s Ted Lasso filming spot inspired me to take on Sadiq Khan as Mayor’

November 10, 2026
All Access London

We bring you the best Premium WordPress Themes that perfect for news, magazine, personal blog, etc. Check our landing page for details.

Follow Us

Browse by Category

  • Apps
  • Business
  • Celebrity
  • Entertainment
  • Fashion
  • Food
  • Gadgets
  • Gaming
  • General
  • Health
  • Lifestyle
  • London
  • London Ent.
  • Mobile
  • Movies
  • Music
  • Politics
  • Reviews
  • Science
  • Sports
  • Startup
  • Tech
  • Travel
  • TV
  • UK

Recent News

David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

David Schwimmer revives Ross Geller’s famous red sweater from Friends for holiday advert

November 10, 2026
Five key accounts from women in Guardian and ITV’s David Walliams investigation

Five key accounts from women in Guardian and ITV’s David Walliams investigation

November 10, 2026
  • About
  • Advertise
  • Privacy & Policy
  • Contact

© 2026 All Access London

No Result
View All Result
  • General
  • Celebrity
  • News
    • London
    • UK
    • Business
    • Politics
    • Science
  • Tech
    • Apps
    • Gadgets
    • Mobile
    • Startup
  • Entertainment
    • London Ent.
    • Gaming
    • Movies
    • Music
    • Sports
    • TV
  • Lifestyle
    • Fashion
    • Food
    • Health
    • Travel
  • Reviews

© 2026 All Access London